My research paper, The Immediate Global Impact of US Monetary Policy, is now available.
Research question
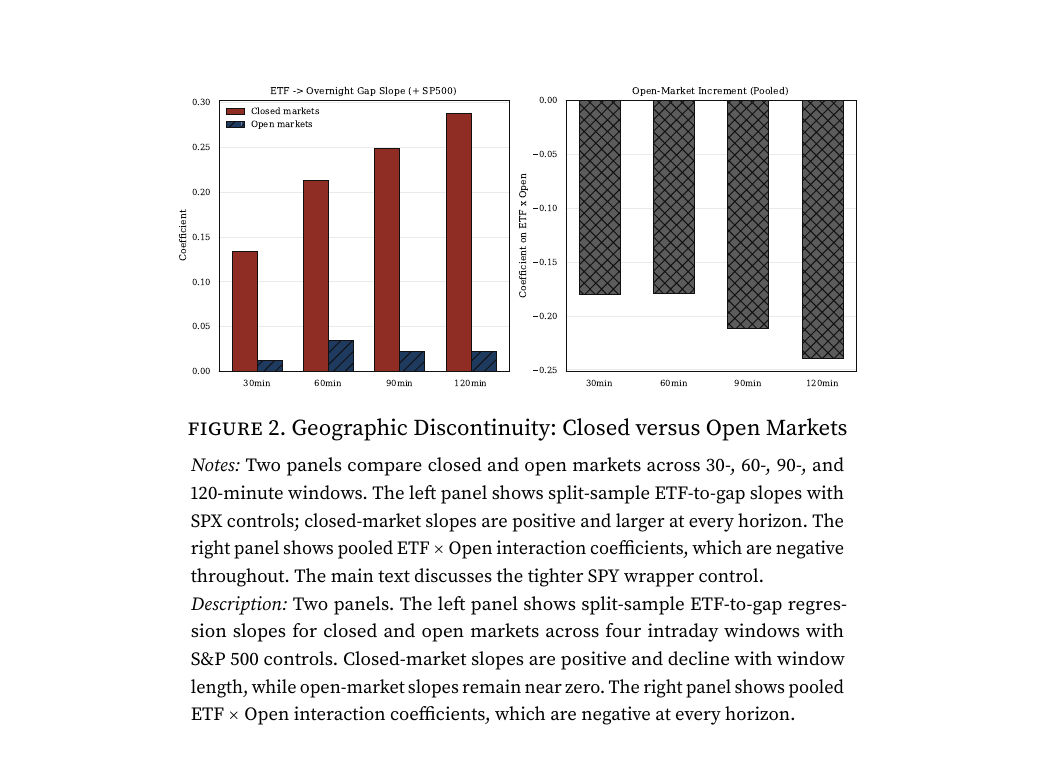
The paper asks how large immediate global equity-market spillovers from US monetary policy are when foreign markets are measured in the same high-frequency window as the FOMC surprise. The key measurement problem is that many local cash markets are closed when FOMC announcements arrive.
Main result
US-traded country ETFs reveal immediate foreign-market repricing that daily local-index designs can miss. A one-standard-deviation contractionary surprise reprices roughly $150-$300 billion in non-US equity wealth within thirty minutes, and roughly half of the response reflects local-currency equity movement rather than exchange-rate translation alone.
Read more
See the full paper page for the research design, results table and citation formats: The Immediate Global Impact of US Monetary Policy. The PDF and SSRN page are also available from the paper page.